Client, stolen-vehicle total loss · Stolen vehicle, total loss · 2017 Subaru Outback Touring
+$4,552after the client came to us
First offer $10,821. The client got it to $14,798 on her own before hiring us, so we count only the increase after that.
CCC ONE valuation check
Upload a photo or PDF of the report. We check its comparables and adjustments against live listings and tell you plainly, for free, whether the number holds up.
No report yet? Pick one for a free estimate. Have the report? Upload it below.
Upload your insurer's valuation report
The CCC or Mitchell report from your insurer. We read it and tell you plainly whether the offer holds up. Free.
Upload your CCC ONE, Mitchell, or repair estimate
PDF, photo, or text — tap to choose, or drag it here
No report yet? Start here instead.
Was your car totaled or repaired?
We calculate your estimate differently depending on what happened.
We use your document only to calculate your estimate. We do not share or sell your information.
Your insurer's report. Your evidence. Your money.
After an accident, carriers use their own tools to minimize what they owe you. We read those numbers and show you what a fair recovery could look like.
Your insurer's valuation report is usually a PDF titled something like "Total Loss Valuation" or "Vehicle Valuation Report" from CCC or Mitchell. It's in your settlement packet, or you can request it from your adjuster.
Diminished value is the gap between what your car was worth before the accident and after, even once repairs are done. You can seek it from an at-fault driver's insurer as part of a liability claim. This is a recognized claim type, not a loophole. We are not your attorney and this is not legal advice.
Reports reviewed and signed by an ASCAA Certified Auto Appraiser (Certificate ASCAA-CERT-9659)
See a sample appraisal report — PDF, 51 pages
What we check
Check them yourself, or upload the report above and we go through each one for you.
The report prices your car from a handful of similar cars for sale or recently sold. If the comparables are wrong, everything after them is wrong.
Many reports rate parts of your car against a “typical” one and take money off for anything rated below it.
Dealer asking prices are often cut by a “projected sold” adjustment, on the theory that cars sell for less than their sticker.
The report values the car it thinks you had. A missing package or option means every comparable is priced as a lesser car.
The last page adds tax and fees and subtracts your deductible. In many states some or all of the replacement tax and fees are owed to you.
If the number holds up, you will hear that too: some reports are fair, and paying anyone to dispute a fair number is a waste. Results vary. Not legal advice. CCC ONE is a trademark of CCC Intelligent Solutions Inc. We are independent and not affiliated with CCC. We are not a law firm.
Documented results
Our first closed paid case, measured from the offer the client had when they came to us. 1 closed so far; 4 more are still open, and we add results here as they close.
Client, stolen-vehicle total loss · Stolen vehicle, total loss · 2017 Subaru Outback Touring
First offer $10,821. The client got it to $14,798 on her own before hiring us, so we count only the increase after that.
Client, third-party total loss · Total loss, the other driver's insurer · 2015 Mercedes-Benz S-Class
The other driver's insurer offered $34,451. After our valuation package it revised its settlement in writing to $39,577, above the figure we asked for. We have asked it to reverse two more deductions, so the claim is still open and this case is not in the closed-case count yet.
A Bay Area client, coached at no charge · Total loss · 2017 Chevrolet Silverado 3500HD
Referred by her body shop. We produced no document: we advised by text and email on comps, her written response and the appraisal clause, and checked the settlement breakdown. The insurer's first offer was $40,916 and its own appraiser later said $34,970; she negotiated the $43,000 herself (10/13/2026). No kit was purchased. Not counted in paid-customer figures.
I was skeptical how this would all work when I first contacted [us] but I have been pleasantly surprised. The process has been easier and faster than I imagined, no doubt due to your diligence and quick responses to all my questions and requests. I am extremely satisfied with your work and the settlement that you were able to generate for our stolen vehicle.
Zoheb was amazing. I couldn't have done this without his guidance. … His communication was great any time I had a question or needed his assistance he was on top of it. Thank again Zoheb for all your help. We greatly appreciate you.
Results vary. Every claim is different, and some recover less or nothing above the insurer's offer. Not legal advice. Figures come from each claim’s own documents.
Why us
$249 or $349, once, and you keep every dollar you recover. Recover under $500 with either kit and we refund your purchase.
We check their CCC or Mitchell valuation line by line against live comparable listings, so your answer is built on their numbers. That first check is free.
An appraisal signed by an ASCAA Certified Auto Appraiser and a demand letter already written in your name, about 2 business days after we have your documents. Fully remote: you upload, read and send.
What each option would cost you on an example $5,000 increase. Illustration only, not a quote from any firm, and many won’t take a claim this size.
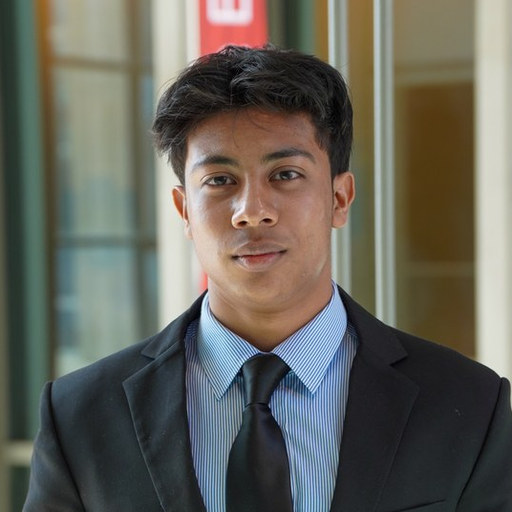
Zoheb Alvi, Co-founder & CEO
 Indiana University Alum
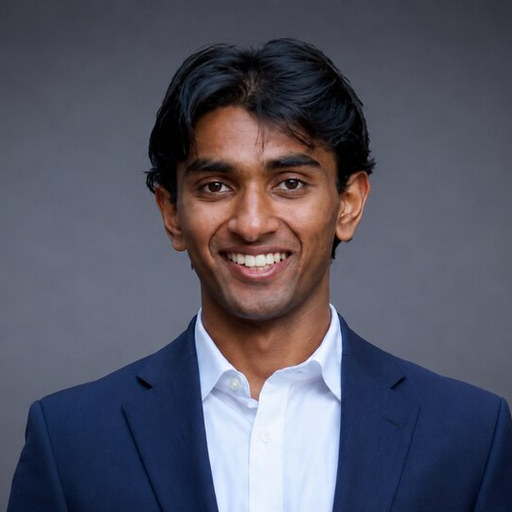
Ajay Donthula, Co-founder & COO
 Princeton University
Reports reviewed and signed by an ASCAA Certified Auto Appraiser (Certificate ASCAA-CERT-9659)
How it works
Free, right now
Upload the insurer's valuation report, a PDF or a photo. We read it and tell you plainly whether the number holds up. No account, no card.
About 2 business days
If it's worth answering, pick a kit. About 2 business days after we have your documents, you get the evidence and a demand letter already written in your name. Full Claim Kit appraisals are signed by an ASCAA Certified Auto Appraiser.
You stay in control
You email the letter to your adjuster, or sign a one-page authorization and we send it for you. Forward whatever they reply and we tell you how to answer.
Check before you sign. Accepting the offer and signing the insurer’s release usually closes the claim, and with it your chance to ask for more.
Pricing
Start with the free check. Pay only if you decide the claim is worth answering.
Your car was totaled
$349
Once, per claim. Or 4 payments at checkout.
Recover under $500? We refund the $349. Terms (not offered in Florida).
Your car was repaired
$249
Once, per claim.
What’s in the kits
Prove the number
Make the demand
Stay on track
Questions
When an insurer pays a total loss claim, the car becomes salvage, so for insured cars the insurer's total-loss decision controls. A 70% repair-cost test applies to self-insured companies (and 50% to repossessed cars). (625 ILCS 5/3-117.1(b))
On a cash settlement, if you buy or lease a replacement within 30 days, the insurer must reimburse the sales tax and title and transfer fees you pay, up to the amount owed on the totaled car's value, if you send proof within 33 days. (50 Ill. Adm. Code 919.80(c)(3)(A)(i))
Section 919.80 sets Illinois' required auto claim practices, including total-loss valuation, replacement offers, tax and fee reimbursement, and written explanations for delayed claims. (50 Ill. Adm. Code 919.80)
Illinois' auto claim regulation lists settling under the policy's appraisal section as one option when you can't buy a comparable car for the total-loss offer, and says that appraisal binds both sides. (50 Ill. Adm. Code 919.80(c)(3))
You can ask the insurer for the full valuation report and question any comparable vehicle or adjustment in it. Many auto policies also contain an appraisal clause that lets each side name an appraiser when they disagree on value. Read your own policy to see whether it has one and what its deadlines are.
One ASCAA Certified Auto Appraiser prepares and signs every report. That is a professional certification. The work is done online from your documents and photos.
No. We tell you what the evidence supports. Whether the insurer changes its offer depends on your vehicle, your market and the insurer.
It’s free and takes a couple of minutes. You’ll know whether the number holds up.
Reports reviewed and signed by an ASCAA Certified Auto Appraiser (Certificate ASCAA-CERT-9659). Not a law firm or a public adjuster; not legal advice.